How to start saving money
Most people know they should save money, but staring at a bank account balance that barely moves can feel discouraging before you even begin. The truth is that learning how to start saving money isn’t about earning a huge salary or making dramatic lifestyle changes overnight. It’s about building small, consistent habits that add up over time. Whether you’re trying to pay off debt, prepare for emergencies, or simply stop living paycheck to paycheck, the path forward starts with a handful of practical steps anyone can follow. This guide breaks down exactly how to build a savings habit that sticks, without the overwhelm or guilt trips so many money articles rely on.
Why It’s Hard to Start Saving Money
Before diving into strategies, it helps to understand why saving feels so difficult in the first place. Rising costs for groceries, rent, and everyday essentials mean many households have less wiggle room than they used to. On top of that, saving requires delayed gratification in a world designed to encourage instant spending, from one-click checkouts to endless subscription services. It’s not a lack of willpower causing the struggle; it’s a lack of structure. Once you create a system that removes decision fatigue and makes saving automatic, the process becomes far less stressful. The good news is that even small, imperfect steps taken consistently will get you further than waiting for the “perfect” financial moment that may never arrive. If you want to dig deeper, our guide on How to Save Money on Groceries Without Coupons covers this in more detail. This is a common part of dealing with start saving money, and it is worth keeping in mind.
Set Clear Financial Goals First
Saving money without a purpose behind it rarely lasts. You need a reason strong enough to keep you motivated when spending feels tempting. Start by writing down your financial goals, both short-term and long-term, so you have something concrete to work toward. This could include: Many people run into this exact issue with start saving money at some point.
- Building a three-to-six-month emergency fund
- Paying off credit card debt or student loans
- Saving for a home down payment
- Planning a wedding, vacation, or big purchase
- Investing for retirement or long-term financial freedom
Once you know what you’re saving for, it becomes much easier to decide how much to set aside each month and where that money should go. A goal with a name and a deadline feels far more real than a vague promise to “save more.” Keeping start saving money in mind here will save you time later on.
Track Your Spending Before You Budget
You can’t fix what you don’t measure. Before creating a budget, spend a few weeks tracking every dollar that leaves your account, from rent and utilities to coffee runs and streaming subscriptions. Many people are surprised to discover how much they spend on small, forgettable purchases that add up over a month. Use a simple spreadsheet, a notebook, or a budgeting app to categorize your expenses. This step alone often reveals easy places to cut back without feeling deprived. Once you see your spending patterns clearly, you’ll have a realistic picture of your finances instead of a guess. That clarity becomes the foundation for every budgeting decision you make going forward, making it far easier to start saving money with confidence instead of frustration. This detail matters more than it seems once start saving money comes up again.
Build a Simple Budget That Works for You
Choose a Budgeting Method You’ll Actually Stick To
There’s no single correct way to budget, so pick a method that matches your personality and lifestyle. Some people thrive with the 50/30/20 rule, which allocates 50 percent of income to needs, 30 percent to wants, and 20 percent to savings and debt repayment. Others prefer zero-based budgeting, where every dollar gets assigned a job before the month begins. If detailed tracking feels overwhelming, a simpler approach like the envelope system, using cash for specific categories, might suit you better. The best budgeting tips aren’t about perfection; they’re about consistency. Choose a system simple enough that you’ll actually maintain it for months, not just the first exciting week before motivation fades. This connects closely with another common issue — see 10 Side Hustles You Can Start This Weekend for more on that. It is one of those small things that makes start saving money easier to manage overall.
Automate Your Savings
One of the most effective money saving strategies is removing yourself from the equation entirely. Set up automatic transfers from your checking account to a savings account right after payday, before you have a chance to spend that money elsewhere. Even a modest amount, like fifty dollars per paycheck, builds momentum and creates a habit that requires no willpower once it’s running. Many banks and apps allow you to schedule these transfers or round up purchases to the nearest dollar, quietly stashing away spare change. Over months and years, these small automated contributions grow into a meaningful cushion. Automation works because it treats savings like a non-negotiable bill rather than an optional afterthought at the end of the month. This is a common part of dealing with start saving money, and it is worth keeping in mind.
Cut Costs Without Feeling Deprived
Saving money doesn’t require giving up everything you enjoy. Instead, look for costs that provide little value relative to what you pay. Review subscriptions you forgot about, negotiate bills like internet or insurance, and consider cooking at home a few extra nights each week. Small swaps, such as brewing coffee instead of buying it daily or canceling an unused gym membership, free up cash without major sacrifice. Here are a few easy places to start: Many people run into this exact issue with start saving money at some point.
- Cancel duplicate or unused streaming subscriptions
- Compare insurance rates annually
- Buy generic brands for household staples
- Meal plan to reduce grocery waste
- Wait 24 hours before non-essential purchases
These changes feel manageable because they don’t touch the things you genuinely value, making it easier to sustain long term. Keeping start saving money in mind here will save you time later on.
Build an Emergency Fund Before Anything Else
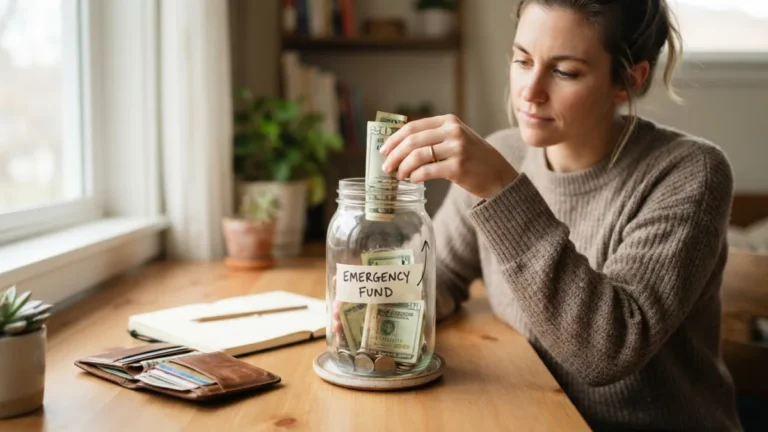
Financial experts consistently recommend prioritizing an emergency fund before tackling other savings goals, and for good reason. Without one, a single unexpected expense, a car repair, medical bill, or job loss, can force you back into debt even after months of careful saving. Start small if needed, aiming for a first milestone of five hundred or a thousand dollars, then build toward three to six months of essential expenses. Keep this money in a separate, easily accessible savings account so it’s available when you need it but not so convenient that you dip into it for everyday spending. Having this safety net in place gives you the confidence to take on other financial goals without the constant fear of one bad month undoing your progress. You might also find our article on Best Free Budgeting Apps Compared helpful here. This detail matters more than it seems once start saving money comes up again.
Use High-Yield Savings Accounts to Grow Your Money
Where you keep your savings matters almost as much as how much you save. A standard checking account typically earns little to no interest, while high-yield savings accounts, often offered by online banks, can provide a meaningfully better return with no added risk. Since these accounts are usually federally insured up to standard limits, your money stays protected while earning more over time. Compare a few options based on interest rates, fees, and accessibility before choosing one. This small adjustment costs nothing extra but lets your money work harder in the background. It’s a simple upgrade that fits naturally into any personal finance plan, especially once you’ve already built the habit of saving regularly. It is one of those small things that makes start saving money easier to manage overall.
Handle Debt Alongside Your Savings Plan
Many people feel they must choose between paying off debt and saving money, but a balanced approach usually works best. High-interest debt, especially credit cards, can grow faster than most savings accounts earn, so it deserves priority. A common approach is to build a small starter emergency fund first, then aggressively pay down high-interest debt while contributing a smaller, steady amount to savings. Once debt is under control, you can redirect those payments toward larger financial goals. Ignoring debt while saving aggressively often means paying more in interest than you earn in returns, which undermines your progress. Tackling both simultaneously, even at a slower pace, keeps you moving forward on every front instead of feeling stuck waiting for one goal to finish before starting another. This is a common part of dealing with start saving money, and it is worth keeping in mind.
Stay Consistent and Adjust as Life Changes
Saving money isn’t a one-time project; it’s an ongoing habit that evolves alongside your income, responsibilities, and goals. Revisit your budget every few months to account for raises, new expenses, or shifting priorities. Celebrate small milestones along the way, hitting your first thousand dollars saved or paying off a credit card, since recognizing progress keeps motivation alive. Life will inevitably bring setbacks, an unexpected expense or a lower-income month, and that’s normal. What matters most is returning to your plan rather than abandoning it entirely. The people who succeed at building wealth over time aren’t necessarily those who never make mistakes; they’re the ones who stay consistent and adjust their approach as circumstances change, treating personal finance as a long-term practice rather than a quick fix. Many people run into this exact issue with start saving money at some point.
Frequently Asked Questions
How much money should I save each month?
A common guideline is to save at least 20 percent of your income, but the right amount depends on your expenses, debt, and goals. Starting with any consistent amount, even a small one, is better than waiting until you can save a large sum. For a related walkthrough, check out Debt Snowball vs. Debt Avalanche: Which Is Faster?. Keeping start saving money in mind here will save you time later on.
What’s the fastest way to start saving money with a low income?
Focus on automating even tiny transfers, cutting one or two unnecessary expenses, and building a small emergency fund first. Consistency matters more than the amount when you’re just getting started. This detail matters more than it seems once start saving money comes up again.
Should I pay off debt before building an emergency fund?
Most experts suggest building a small starter emergency fund of a few hundred dollars first, then focusing on high-interest debt while continuing modest, steady savings contributions. It is one of those small things that makes start saving money easier to manage overall.
What’s the difference between a savings account and an emergency fund?
A savings account is simply where you store money, while an emergency fund is a specific savings goal meant to cover unexpected expenses. Many people keep their emergency fund in a dedicated high-yield savings account separate from other savings goals. This is a common part of dealing with start saving money, and it is worth keeping in mind.
How do I stay motivated to keep saving money?
Set clear, specific financial goals, track your progress regularly, and celebrate milestones along the way. Automating your savings also removes the need for daily motivation altogether. Many people run into this exact issue with start saving money at some point.