Budgeting Methods Compared: Which One Actually Works?
Most people who fail at budgeting don’t fail because they lack discipline. They fail because they picked a system that doesn’t match how their brain actually works. When you start looking at budgeting methods compared side by side, a pattern jumps out fast: no single approach is objectively “best.” The right one depends on your income, your personality, and how much time you’re willing to spend tracking every dollar. This article breaks down the most popular budgeting systems, weighs their pros and cons, and helps you figure out which one might finally stick for you.
Why Your Budgeting Method Matters More Than the Numbers
It’s tempting to think budgeting is just math, but the method you choose shapes your habits far more than the actual figures do. A rigid system can feel suffocating to someone who values flexibility, while a loose one can feel chaotic to someone who craves structure. Think of a budgeting method as a set of guardrails rather than a strict rulebook. The goal isn’t to punish yourself for spending money; it’s to build a repeatable habit that keeps your spending aligned with your goals. That’s why, when budgeting methods compared against real-life results, the “winner” usually turns out to be whichever one a person actually keeps using after the first three months, not the one that looks best on paper. If you want to dig deeper, our guide on Best Free Budgeting Apps Compared covers this in more detail. This is a common part of dealing with budgeting methods compared, and it is worth keeping in mind.
The 50/30/20 Rule Explained
The 50/30/20 rule splits your after-tax income into three simple buckets: 50 percent for needs, 30 percent for wants, and 20 percent for savings and debt repayment. It’s popular because it’s easy to remember and doesn’t require tracking every single purchase. You just check in periodically to see if your spending roughly matches those percentages. This makes it a great entry point for beginners who feel overwhelmed by spreadsheets or apps. The downside is that it can feel too loose for people with irregular income or big debt loads, since 20 percent toward savings might not be nearly enough, or might be unrealistic if rent alone eats up more than half your paycheck. Many people run into this exact issue with budgeting methods compared at some point.
Who This Method Works Best For
This approach tends to suit people with steady paychecks and relatively simple financial lives, like young professionals renting an apartment with no major debt beyond a student loan. It also works well for anyone who has tried detailed budgeting apps before and abandoned them because tracking every coffee purchase felt exhausting. If you want structure without obsessive tracking, this is often a solid starting point before moving to something more detailed later on. Keeping budgeting methods compared in mind here will save you time later on.
Zero-Based Budgeting: Every Dollar Gets a Job
Zero-based budgeting flips the script by requiring you to assign every single dollar of income to a category before the month even begins, so your income minus your allocations equals zero. Nothing floats around unassigned. This method forces intentionality; you can’t just let extra cash sit around and quietly disappear on random purchases. People who use zero-based budgeting often report feeling more in control because they know exactly where their money is going before they spend it, not after. The trade-off is time. This method demands more upfront planning and regular adjustments when unexpected expenses pop up, which can feel like a part-time job if you’re new to it or juggling a busy schedule. This connects closely with another common issue — see Zero-Based Budgeting Explained (With Free Template) for more on that. This detail matters more than it seems once budgeting methods compared comes up again.
The Envelope Budgeting System (Old School but Effective)
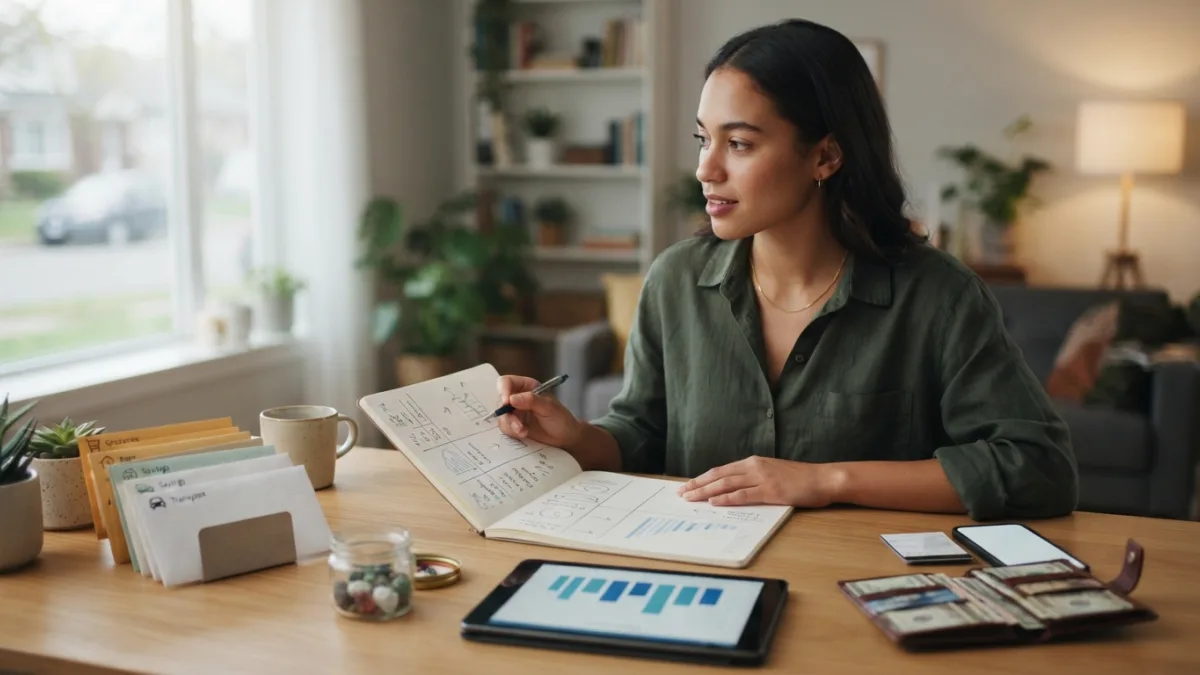
Long before budgeting apps existed, people used the envelope system, physically dividing cash into labeled envelopes for groceries, entertainment, gas, and so on. Once an envelope is empty, spending in that category stops until next month. Today, many people replicate this digitally through banking apps that let you create sub-accounts or virtual envelopes, but the core principle stays the same. This method is especially effective for people who overspend on cards because it makes limits feel tangible and immediate. The downside is convenience; carrying cash isn’t always practical, and digital versions require some setup. Still, for anyone who struggles with impulse spending, this hands-on approach often produces faster results than a spreadsheet ever could. It is one of those small things that makes budgeting methods compared easier to manage overall.
Other Methods Worth Knowing
Beyond the three heavy hitters above, a few other approaches deserve a mention. The “pay yourself first” method prioritizes savings the moment income arrives, before any bills or discretionary spending happens, which works well for people who struggle to save consistently. Values-based budgeting asks you to rank what matters most to you personally, then allocate money accordingly, even if that means spending more on travel and less on dining out. There’s also the reverse budget, which is essentially a stripped-down version of pay-yourself-first focused entirely on automating savings and letting the rest flow freely. None of these are wrong; they simply serve different personalities and financial situations. This is a common part of dealing with budgeting methods compared, and it is worth keeping in mind.
Budgeting Methods Compared: Side-by-Side Table
Sometimes the easiest way to decide is to see everything laid out at once. Below is a quick snapshot of how these budgeting methods compared on the factors that matter most: time investment, flexibility, and who tends to benefit most from each one. You might also find our article on The 50/30/20 Budget Rule: Does It Actually Work? helpful here. Many people run into this exact issue with budgeting methods compared at some point.
| Method | Time Required | Flexibility | Best For |
|---|---|---|---|
| 50/30/20 Rule | Low | High | Beginners, steady income earners |
| Zero-Based Budgeting | High | Low | Detail-oriented planners, variable income |
| Envelope System | Medium | Medium | Impulse spenders, cash-preferring users |
| Pay Yourself First | Low | High | Inconsistent savers, automation lovers |
| Values-Based Budgeting | Medium | High | People with strong lifestyle priorities |
So Which Is the Best Budgeting Method for You?
Here’s the honest truth: the best budgeting method is the one you’ll still be using six months from now. If you hate tracking every purchase, zero-based budgeting will probably burn you out no matter how effective it looks in theory. If you’re drowning in unassigned spending and can’t figure out where your paycheck goes, the loose structure of the 50/30/20 rule might not give you enough guardrails. Try one method for a full month before judging it. Financial habits take time to feel natural, and switching systems every two weeks will leave you more confused than when you started. Give yourself permission to adjust and blend methods as your life circumstances change. Keeping budgeting methods compared in mind here will save you time later on.
Personal Finance Budgeting Tips to Make Any Method Stick
Regardless of which system you choose, a few habits make any budget more effective. Track your spending for at least two weeks before setting category limits, so your numbers reflect reality rather than guesswork. Automate what you can, especially savings transfers, so good habits don’t rely on willpower alone. Review your budget weekly instead of monthly; small check-ins catch problems before they snowball. Build a small buffer for irregular expenses like car repairs or medical costs, since forgetting these is one of the most common reasons budgets fall apart. Finally, don’t aim for perfection. A budget you adjust and stick with imperfectly beats a flawless plan you abandon after one bad week. This detail matters more than it seems once budgeting methods compared comes up again.
Frequently Asked Questions
What is the easiest budgeting method for beginners?
The 50/30/20 rule is generally considered the easiest starting point because it requires minimal tracking and gives broad, flexible categories rather than dozens of specific limits. For a related walkthrough, check out 20 Frugal Living Tips That Don't Feel Like Sacrifice. It is one of those small things that makes budgeting methods compared easier to manage overall.
Is zero-based budgeting better than the 50/30/20 rule?
Neither is universally better. Zero-based budgeting offers more control and precision, while the 50/30/20 rule offers simplicity and speed. The right choice depends on how much time you want to spend managing your money. This is a common part of dealing with budgeting methods compared, and it is worth keeping in mind.
Can I combine different budgeting methods?
Yes, many people blend approaches, such as using pay-yourself-first for savings while applying envelope budgeting to variable spending categories like groceries and entertainment. Many people run into this exact issue with budgeting methods compared at some point.
How often should I review my budget?
A weekly check-in works well for most people, since it’s frequent enough to catch overspending early without becoming a tedious daily chore. Keeping budgeting methods compared in mind here will save you time later on.
Does the envelope system still work if I don’t use cash?
Yes. Many banking apps now offer digital sub-accounts or spending categories that mimic the envelope system, giving you the same spending limits without carrying physical cash.