How to Set Financial Goals You’ll Actually Reach
Most New Year’s resolutions about money die by February, and it’s not because people lack willpower. The real problem is how they set financial goals in the first place. Vague wishes like “save more” or “get out of debt” sound nice, but they don’t give your brain anything concrete to grab onto. If you want a savings plan that actually sticks, you need a system, not just good intentions. This guide walks through practical, realistic steps to set financial goals you can track, adjust, and actually reach, without the burnout that usually comes with big money resolutions.
Why Most Money Goals Fall Apart
Before fixing the problem, it helps to understand it. Many people set financial goals that are either too big, too vague, or disconnected from their daily habits. Saying “I want to be debt-free” doesn’t tell you what to do on a Tuesday afternoon when you’re deciding whether to order takeout. Other times, goals fail because they’re borrowed from someone else’s life. A goal to save six months of expenses might make sense for a freelancer with unpredictable income, but it could feel pointless to someone with steady employment and different priorities. Personal finance tips only work when they’re personal. The first step toward real progress is admitting that generic advice needs to be shaped around your actual numbers and lifestyle. If you want to dig deeper, our guide on Best Free Budgeting Apps Compared covers this in more detail. This is a common part of dealing with set financial goals, and it is worth keeping in mind.
Start With Smart Financial Goals, Not Big Wishes
The term “smart financial goals” gets thrown around a lot, but the framework behind it genuinely works when applied honestly. A goal should be specific, measurable, achievable, relevant, and time-bound. Instead of “save more money,” try “save $3,000 for an emergency fund by December by setting aside $250 a month.” That single sentence tells you the amount, the deadline, and the monthly action required. It also lets you check your progress at any point instead of guessing. When you set financial goals this way, you remove the ambiguity that usually leads to procrastination. You’re no longer hoping things work out; you’re following a plan with clear checkpoints built in from day one. Many people run into this exact issue with set financial goals at some point.
Turn Vague Dreams Into Numbers
A lot of financial dreams stay stuck because they never get translated into actual figures. “I want to travel more” is a feeling, not a plan. “I want to save $1,800 for a trip in ten months” is something you can act on immediately. Sit down and write out every financial goal you’re currently carrying around in your head, then attach a number and a date to each one. This doesn’t have to be perfect on the first try. The point is to move from abstract hope to something you can measure weekly or monthly. Once numbers are attached, your brain treats the goal differently, more like a project with steps rather than a wish you’re waiting on. Keeping set financial goals in mind here will save you time later on.
Break Big Goals Into Smaller Money Management Goals
Paying off $15,000 in debt or saving for a house down payment can feel overwhelming when you look at the whole mountain at once. Breaking that big goal into smaller money management goals makes the climb feel doable. Instead of focusing on the entire debt balance, focus on paying off the first $1,000, then the next $1,000. Instead of a full down payment, aim for a smaller milestone every three months. These mini-goals give you frequent wins, and frequent wins keep motivation alive far longer than a single distant finish line. This approach also makes it easier to notice when something isn’t working, since you’re checking in regularly instead of only looking up once a year to find you’ve barely moved. This connects closely with another common issue — see Zero-Based Budgeting Explained (With Free Template) for more on that. This detail matters more than it seems once set financial goals comes up again.
Follow Clear Financial Planning Steps
Good intentions need structure behind them, and that’s where solid financial planning steps come in. Start by getting an honest picture of where you stand right now: your income, your fixed expenses, your debts, and whatever you’re currently saving. From there, decide which goal matters most and rank the rest below it. Trying to tackle five goals at full speed at once usually means none of them get proper attention. Pick one or two priorities, put the others on a slower track, and revisit the full list every few months. This kind of ordered approach keeps you from spreading your money and attention so thin that nothing actually improves. It is one of those small things that makes set financial goals easier to manage overall.
- List all your income sources and monthly expenses
- Identify your top one or two financial priorities
- Set a realistic timeline for each goal
- Decide how much you can consistently contribute each month
- Review and adjust the plan every few months
Use Budgeting Strategies That Actually Match Your Life
A budget only works if it fits how you actually live, not how you think you should live. Some people do well with a strict percentage-based budget, splitting income into needs, wants, and savings. Others prefer a simpler approach: pay every bill and savings goal first, then spend whatever remains freely without guilt. Neither method is objectively better than the other. What matters is picking budgeting strategies that you can stick with for months, not just a few enthusiastic weeks. If a budget feels like a punishment, you’ll likely abandon it. Test a method for a full month before deciding it’s not working, since it often takes a few pay cycles to see whether a system truly fits your spending patterns. This is a common part of dealing with set financial goals, and it is worth keeping in mind.
Automate What You Can
Willpower runs out, especially by the end of a long week when a tempting purchase pops up. Automation removes that decision entirely. Set up automatic transfers to your savings account right after payday, before you have a chance to spend the money elsewhere. Many banks also let you automate extra debt payments or round up purchases to add small amounts to savings. These small automated habits add up quietly in the background while you focus on everything else in life. When you set financial goals and automatically fund them, you’re far less likely to skip a month simply because you forgot or got busy with something more urgent. You might also find our article on how to start saving money helpful here. Many people run into this exact issue with set financial goals at some point.
Short-Term vs. Long-Term Goals
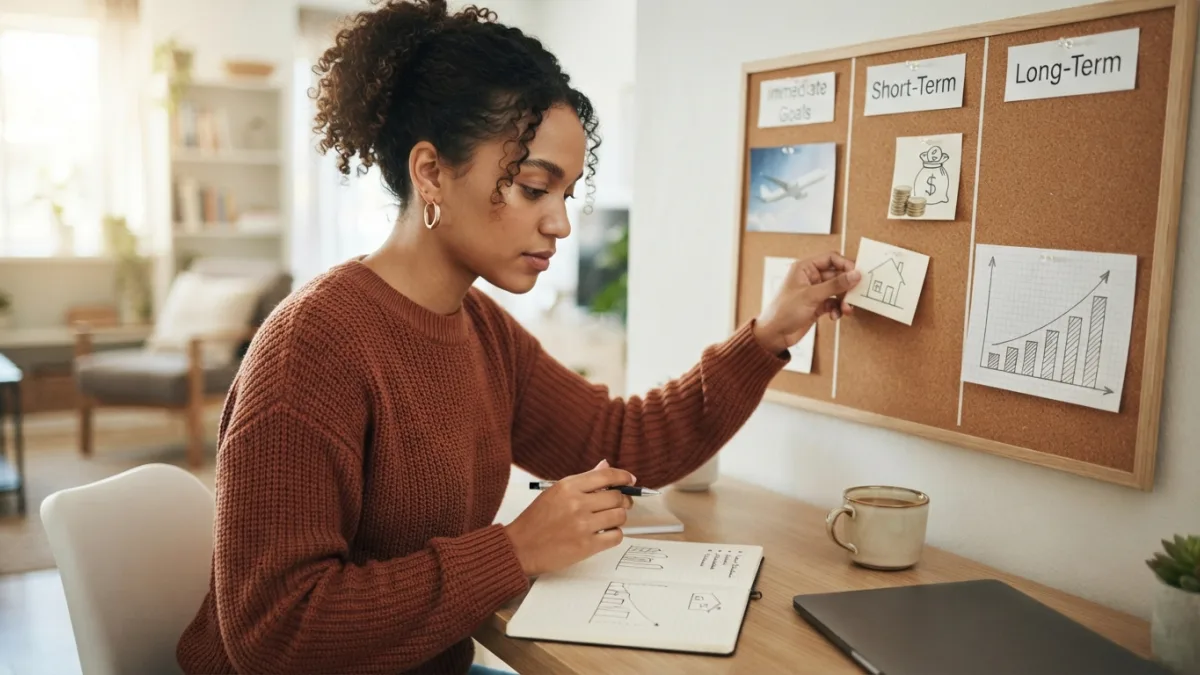
Not every financial goal deserves the same treatment or timeline, and mixing them together often causes confusion. Short-term goals usually take under a year and might include building a small emergency cushion or paying off a credit card. Long-term goals stretch over several years and might involve retirement savings or a home purchase. Treating both the same way often backfires, since long-term goals need different tools like retirement accounts or investment plans, while short-term goals usually just need a dedicated savings account. Here’s a simple breakdown to help separate the two categories clearly. Keeping set financial goals in mind here will save you time later on.
| Goal Type | Typical Timeline | Best Tool |
|---|---|---|
| Short-term (emergency fund, small debt) | Under 1 year | High-yield savings account |
| Medium-term (car, wedding, vacation) | 1 to 5 years | Dedicated savings account or CD |
| Long-term (retirement, home purchase) | 5+ years | Retirement account or investment portfolio |
Common Mistakes That Derail Progress
Even well-planned goals can fall apart if a few common traps go unnoticed. One frequent mistake is setting too many goals at once, which splits your money so thin that none of them move forward meaningfully. Another is ignoring small wins along the way, which drains motivation faster than people expect. A third mistake is refusing to adjust a goal when life circumstances change, like a new job, a medical expense, or a rent increase. Sticking rigidly to an old plan that no longer fits your income only leads to frustration and eventual quitting. Recognizing these patterns early gives you a chance to correct course before an entire year’s effort gets wasted on a plan that stopped making sense months ago. This detail matters more than it seems once set financial goals comes up again.
Adjust Your Goals as Life Changes
Financial goals aren’t meant to be carved in stone. Your income, priorities, and responsibilities will shift over time, and your goals should shift with them. If you get a raise, that might mean increasing your monthly savings contribution rather than letting lifestyle creep quietly absorb the extra money. If an unexpected expense hits, it’s fine to temporarily pause a savings goal and redirect funds toward the emergency instead. The people who succeed long-term with money aren’t the ones who never adjust their plans; they’re the ones who check in regularly and make honest updates. Revisiting your goals every few months, rather than only once a year, keeps the plan realistic and prevents small problems from turning into major setbacks later. For a related walkthrough, check out How to Save Money on Groceries Without Coupons. It is one of those small things that makes set financial goals easier to manage overall.
Reaching your financial goals isn’t about finding one perfect method that works for everyone. It’s about building a system that fits your actual income, your real habits, and your specific priorities, then checking in on it often enough to make small corrections along the way. Start small, track your progress honestly, and don’t be afraid to change course when something isn’t working. The goals that stick aren’t necessarily the biggest or boldest ones; they’re the ones broken into steps small enough to follow through on, month after month, until they quietly become reality. This is a common part of dealing with set financial goals, and it is worth keeping in mind.
Frequently Asked Questions
How many financial goals should I focus on at once?
Most people do best focusing on one or two priorities at a time. Spreading attention across five or six goals usually slows down progress on all of them. Many people run into this exact issue with set financial goals at some point.
What’s the difference between a financial goal and a budget?
A financial goal is the outcome you’re aiming for, like saving $5,000. A budget is the tool you use to manage your income and expenses so you can actually reach that goal. Keeping set financial goals in mind here will save you time later on.
How often should I review my financial goals?
Checking in every three months works well for most people. It’s frequent enough to catch problems early without turning your finances into a constant source of stress. This detail matters more than it seems once set financial goals comes up again.
Should I pay off debt or save money first?
It often makes sense to build a small emergency cushion first, then focus on high-interest debt, while still contributing a small amount to savings along the way. It is one of those small things that makes set financial goals easier to manage overall.
What if I miss a month toward my savings goal?
One missed month won’t ruin your progress. Adjust the timeline slightly, keep going, and avoid the trap of quitting the entire plan over a single setback. This is a common part of dealing with set financial goals, and it is worth keeping in mind.