Debt Snowball vs. Debt Avalanche: Which Is Faster?
Staring down multiple credit card bills, a car loan, and maybe a personal loan can feel overwhelming, and picking the wrong payoff plan can cost you months or even years of extra payments. That’s why the debt snowball vs avalanche debate matters so much to anyone trying to dig out of debt. Both strategies work, but they work in different ways, and the one that gets you debt-free fastest isn’t always the one that feels easiest. Understanding how each method actually functions, in real dollars and real time, is the first step toward choosing a debt payoff strategy you’ll actually stick with until the last balance hits zero.
What Is the Debt Snowball Method?
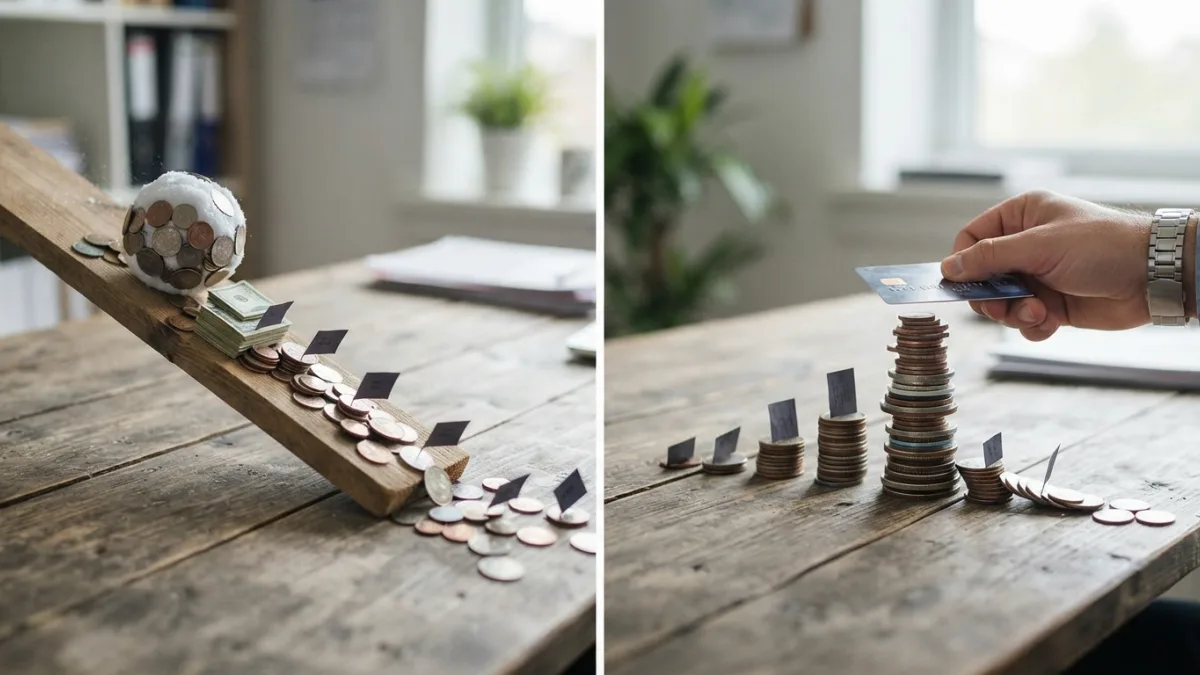
The snowball method asks you to list every debt from smallest balance to largest, ignoring the interest rate completely. You keep making minimum payments on everything except the smallest debt, and you throw every extra dollar you can find at that one. Once it’s paid off, you take the money you were putting toward it and roll it into the next smallest balance. The list gets shorter, but each payment gets bigger, kind of like a snowball rolling downhill and picking up size as it goes. This approach was popularized by financial personality Dave Ramsey, and its biggest selling point is momentum. Knocking out a full debt early gives you a quick win, and that small victory often keeps people motivated when the finish line still feels far away. If you want to dig deeper, our guide on How to Build Your First Budget (Beginner's Guide) covers this in more detail. This is a common part of dealing with debt snowball vs avalanche, and it is worth keeping in mind.
What Is the Debt Avalanche Method?
The avalanche method flips the order. Instead of ranking debts by balance, you rank them by interest rate, from highest to lowest. You still pay the minimums on everything, but your extra cash goes toward whichever debt charges you the most in interest. Once that high interest debt disappears, you move to the next highest rate, and so on down the line. Mathematically, this is the more efficient path because it reduces the total interest you pay over the life of your debt. If you have a credit card charging 24 percent alongside a personal loan at 9 percent, the avalanche method tackles that credit card first, even if its balance happens to be larger than the loan. It’s a numbers-driven approach built for people who want to pay off debt faster in terms of total cost. Many people run into this exact issue with debt snowball vs avalanche at some point.
Debt Snowball vs Avalanche: Which Pays Off Debt Faster?
Here’s the honest answer: the avalanche method almost always saves more money and, in most cases, gets you to zero balance sooner too, because less of your payment gets eaten up by interest charges. The snowball method can occasionally take a bit longer and cost a little more in interest over time. But the gap isn’t always huge, especially if your debts have similar interest rates or if the smallest balance also happens to carry a high rate. The real difference shows up when you have a mix of low-balance, low-rate debts and high-balance, high-rate debts. In that situation, the avalanche method’s savings become much more noticeable, sometimes amounting to hundreds or even thousands of dollars depending on how much debt you’re carrying and how long it takes to pay off. Keeping debt snowball vs avalanche in mind here will save you time later on.
| Factor | Debt Snowball | Debt Avalanche |
|---|---|---|
| Payoff order | Smallest balance first | Highest interest rate first |
| Total interest paid | Usually higher | Usually lower |
| Speed to debt-free | Slightly slower in most cases | Typically faster |
| Motivation factor | High, quick early wins | Lower at first, builds later |
| Best for | People who need momentum | People focused on math and savings |
Why the Math Doesn’t Always Win
If the avalanche method saves more money, why doesn’t everyone use it? Because paying off debt isn’t purely a math problem, it’s also a behavior problem. Plenty of people start a debt payoff plan with great intentions and quit a few months later because progress feels invisible. When your extra payments go toward a large, high-interest balance, that number can shrink so slowly that it feels like you’re not getting anywhere. The snowball method solves that emotional problem by giving you a completed, zero-balance account within weeks or a couple of months, which creates a sense of accomplishment. That feeling of crossing something off the list can be the difference between staying committed to a plan and giving up halfway through. Personal finance is often more about behavior than spreadsheets. This detail matters more than it seems once debt snowball vs avalanche comes up again.
Which Strategy Fits Your Personality?
Choosing between the snowball method and the avalanche method really comes down to knowing yourself. Ask a few honest questions before deciding: It is one of those small things that makes debt snowball vs avalanche easier to manage overall.
- Do you get discouraged easily if progress feels slow?
- Are you more motivated by visible wins or by long-term savings?
- Do you tend to stick with financial plans once you commit, or do you lose steam quickly?
- Is one of your high interest debts also a small balance, meaning both methods would suggest paying it first?
If you thrive on quick wins and worry about losing motivation, the snowball method might keep you in the game longer, even if it costs a bit more. If you’re disciplined, comfortable with delayed gratification, and want to minimize interest costs, the avalanche method is probably your better fit. This is a common part of dealing with debt snowball vs avalanche, and it is worth keeping in mind.
A Simple Example With Real Numbers
Picture three debts: a $500 store card at 26 percent interest, a $3,000 credit card at 19 percent, and a $6,000 personal loan at 8 percent. With the snowball method, you’d attack the $500 card first since it’s the smallest balance, even though it also happens to carry the highest rate here. With the avalanche method, you’d also start with that same card, because it has the highest interest rate. In this case, both strategies agree on the first target, so there’s no real conflict. But imagine that $500 balance had a 6 percent rate instead. The snowball method would still start there because of its size, while the avalanche method would jump straight to the credit card charging 19 percent, changing your total interest paid by the end. Many people run into this exact issue with debt snowball vs avalanche at some point.
Can You Combine Both Methods?
Many people don’t realize they can build a hybrid approach that borrows from both strategies. One common version starts with the snowball method to knock out one or two small debts quickly for that early motivation boost, then switches to the avalanche method for the remaining balances to maximize interest savings from that point forward. Another version simply weighs both balance size and interest rate together, creating a custom order that feels like a reasonable middle ground. There’s no rule that says you must follow either method exactly as written. The best debt payoff strategy is the one you’ll actually follow through to the end, so adjusting the plan to match your own motivation triggers and financial situation is completely reasonable, and often smarter than rigidly sticking to a formula. Keeping debt snowball vs avalanche in mind here will save you time later on.
How to Choose the Right Debt Payoff Strategy for You
Before locking in a plan, list every debt you owe along with its balance, interest rate, and minimum payment. Add up how much extra money you can realistically put toward debt each month beyond the minimums. Then run both scenarios, snowball and avalanche, either with a simple spreadsheet or one of the many free calculators available online, and compare the total time and total interest for each. If the difference in interest is small, let your personality make the final call. If the difference is large, especially because you’re carrying a card with a very high interest rate, the extra discipline required by the avalanche method might be worth the savings. Whichever you choose, automating your extra payments removes the temptation to skip a month. This detail matters more than it seems once debt snowball vs avalanche comes up again.
There’s no universally “correct” winner in the debt snowball vs avalanche debate, because the fastest method on paper isn’t always the fastest method in practice for a real person with real habits. The avalanche method wins on pure math almost every time, shaving off interest and often shortening your payoff timeline. The snowball method wins on momentum, turning a long, discouraging process into a series of small, motivating victories. What actually matters most is picking a strategy, sticking with it, and staying consistent month after month. Either path, followed faithfully, will get you to debt freedom. The one you abandon after three months, no matter how mathematically superior, will get you nowhere at all. It is one of those small things that makes debt snowball vs avalanche easier to manage overall.
Frequently Asked Questions
Which method saves more money overall, snowball or avalanche?
The avalanche method almost always saves more money because it targets high interest debt first, reducing the total interest that accumulates over time. The snowball method can cost a bit more, though the difference varies depending on your specific balances and rates. This is a common part of dealing with debt snowball vs avalanche, and it is worth keeping in mind.
Is the debt snowball method ever faster than the avalanche method?
It can be, but only in specific situations, such as when the smallest balance also carries a high interest rate, or when someone loses motivation and stops following the avalanche plan altogether. Consistency often matters more than the small mathematical edge one method has over the other. Many people run into this exact issue with debt snowball vs avalanche at some point.
Can I switch from one method to the other partway through?
Yes, plenty of people start with the snowball method for early motivation and switch to the avalanche method once they build confidence. There’s no penalty for adjusting your strategy as your habits and priorities change. Keeping debt snowball vs avalanche in mind here will save you time later on.
Do both methods require the same minimum payments?
Yes, both strategies require you to keep making minimum payments on every debt except the one you’re actively targeting. The difference lies only in which debt receives your extra payment each month. This detail matters more than it seems once debt snowball vs avalanche comes up again.
Which method is better for someone with only high interest credit card debt?
If all your debts carry similarly high interest rates, the order matters less, and either method will produce close to the same results. In that case, choosing the debt payoff strategy that keeps you most motivated is usually the smarter move. It is one of those small things that makes debt snowball vs avalanche easier to manage overall.